Home Blog Page 23

What is the Tallyman Axis Bank Login Process? Uses, Benefits & Services

0
tallyman axis bank

The Internet and technology are reworking the economic area. These days, banking is easy and only for some clicks. Every bank in the Axis Tallyman Bank place is improving the experience for its clients. India is home to both public and private banks. One personal bank that stands proud of its incredible security and purchaser care is Tallyman Axis Bank. Your login credentials are required to access Axis Bank through Tallyman. Let’s look at how Tallyman Bank makes use of benefits and services, in addition to how to log in.

In this article, we know the current features of Tallyman Axis Login, that increase teamwork and collaboration among users.

What Is Tallyman Axis Login?

Tallyman Axis Login makes it easy for you to access a gate designed for druggies of the Tallyman Axis application program, a comprehensive result for credit score hazard operation and debt collection. This login device serves as the gateway for legal work to pierce the Axis platform, imparting functionalities comparable to debtor shadowing, payment processing, and analytics gear.

The users may additionally accurately control their bills, take care of series conditioning, and generate reviews to expedite debt restoration methods with the Tallyman Axis Login. This centralized login medium ensures records integrity and confidentiality, empowering institutions to successfully navigate and optimize their credit operation strategies simply and confidently.

Also Read:- What is money.rumusrumus.com | What is Section 80GG of ITR? | Marcos Commando Salary

Tallyman Axis Login Process Guide

When you join up on the site, you want to log in on every occasion you need to use it. It’s important to follow the login steps similar to what you probably did whilst you signed up. Here’s a way to log in

  • Open a web browser you use on your tool. You must have stable internet connectivity.
  • Look for the official Tallyman Axis Bank login site. You can also click on this link: https://collections.Axisbank.Co.In/collections/
  • After you click on the link, you’ll see the homepage. Enter your Tallyman username and password.
  • Check your records carefully, then click on ‘Login’ to complete. Once you’re logged in, you may start the use of your dashboard.

Remember, you can only log in after you’ve completed signing up. So, register yourself here.

How Does The Tallyman Axis Bank Login Work?

Those who are new may know how the Tallyman Axis Bank login works. You will find the information in this section.

The Tallyman Axis Bank series gives a user-friendly and easy-to-use experience. To get started, you first have to sign in to the portal. This procedure is brief and straightforward – all you need to do is provide the vital data. This consists of:

  • Web browsers include Firefox or Chrome
  • Username or Email
  • Official login site
  • Password

Key Features of Tallyman Axis Bank

Key Features of Tallyman Axis Bank

Here are various features of the axis bank tallyman

  1. Real-time Reconciliation: Tallyman Axis Bank boasts real-time reconciliation, a function that robotically fits bank statements together with your Tally information. This eliminates guide information entry and reduces the risk of mistakes, saving you valuable time and resources.
  2. Automated Transactions: Streamline your workflows with computerized transactions. Schedule habitual payments like seller invoices or employee salaries directly from your Tally application program. This ensures well-timed payments and removes the need for guide transfers.
  3. Inventory Management: Gain higher control over your stock with Tallyman’s integration. Track stock stages, control purchase orders, and generate reviews at once in your Tally application program. This improves decision-making and allows you to optimize inventory control.
  4. Comprehensive Financial Services: Beyond fundamental banking capabilities, Tallyman Axis Bank gives a complete suite of financial services tailor-made to satisfy clients’ numerous needs. Tallyman Axis Bank presents a one-stop solution for all financial wishes, from savings and checking money owed to loans, investments, and insurance products. This range of services removes the need for clients to juggle multiple money owed and systems, streamlining their financial control technique and saving them effort and time.

Must Read:- IPS Officer Salary | Data Scientist Salary | CTC Full Form

Tallyman Axis Bank Uses

This application has a digital notebook to hold data and provide an explanation for budget plans, reducing the chance of lacking important info.

  • This application reduces the chance of overlooking crucial factors which include a digital pocketbook to explain budget thoughts and hold information.
  • It helps enterprise transactions and inventory market monitoring.
  • Using the given information solves complex financial troubles and gives the right fee required.
  • It gives up-to-date financial data and data to help you in making knowledgeable decisions.
  • It additionally gives different huge abilities, consisting of superior visuals and the capacity to make large choices based on data from the app, much like a money lender.
  • Singapore might do this when reading financial records to give a range of services.

What are the Benefits of Axis Bank Tallyman?

Curious about the benefits of the use of the Tallyman Axis Collection portal? Let’s tell you about it.

1) Speed, Reliability, and Ease of Use

The portal is known for its speedy, dependable, and user-friendly interface, permitting customers to address several banking activities including bill payments and cash transfers with just a few clicks.

2) 24×7 Accessibility

Tallyman Axis Bank prioritizes convenience and Accessibility, providing clients with a user-friendly platform to control their bills from everywhere at any time. Through its intuitive interface and mobile apps, customers can easily check balances, transfer funds, pay payments, and transactions with only some clicks. This Accessibility empowers clients to take control of their budget on their terms, whether at home, in the office, or anywhere.

3) Diverse Financial Services

In addition to simple banking services, Tallyman provides a range of financial services, increasing the scope of what customers can accomplish on the platform.

4) Accessible Customer Support

Similar to traditional bank branches, Tallyman Collection guarantees that customer support is without trouble available. Users can reach out to the guide team whenever assistance is needed.

Also Read:- Salary Slip Format in Excel, Word, and PDF | BSc Nursing Salary | Sundar Pichai Salary

Tallyman Axis Services

This application is designed for banking establishments and has lots of features. Here are some key features:

  • Facilitates easy money control.
  • Provides short access to account data.
  • Maintains a document of preceding transactions.
  • Displays designated data concerning payments and withdrawals.
  • Offers an overview of account interest.
  • Provides access to account records at any time and from any area. These represent the primary functionalities of Tallyman Axis Bank.

Conclusion

Tallyman Axis stands proud as an effective device for addressing business budgets. Its ease of use, combined with effective functions and dependable aid, makes it a vital asset for any business aiming to streamline financial operations. Whether you are a startup or an established organization, Tallyman Axis offers the tools and versatility to control your finances with efficiency and simplicity, adapting to your enterprise’s growing needs and assisting you to live compliant in dynamic enterprise surroundings.

FAQ’s:-

1. What is the Tallyman Axis Bank?

Tallyman Axis is a financial control platform designed to streamline various business accounting tasks.

2. What Are the Crucial Capabilities of the Tallyman Axis Bank?

Some key features encompass a user-friendly interface, 24/7 customer service, robust accounting capabilities, and assistance for a couple of currencies.

3. How Does Tallyman Axis Bank Assist Businesses?

Tallyman Axis Bank automates repetitive tasks, saves time, and reduces agencies’ need for manual calculations.

4. Can Each Specialist and Novice Use the Tallyman Axis Bank?

Yes, Tallyman Axis offers a user-friendly interface suitable for seasoned specialists and learners.

Recommended:-

1.DGP Salary Per Month
2.3 LPA in Hand Salary
3.SSC GD Salary After 5 Years
4.President of India Salary
5.7 LPA in Hand Salary

Standard Deduction for Salaried Individuals in New & Old Tax Regime 2024

0
Standard Deduction for Salaried Individuals

To claim any tax deduction, it is mandatory to have valid proof that shows the real investment or rate has been incurred. But what if we are saying there’s one tax deduction that you could claim with no investment proof? We are talking about standard deduction. It is a flat deduction available to all salaried individuals with no investment proof. In this blog, we will dive deeper to learn what a preferred deduction is, its eligibility, and the way it works.

What is Standard Deduction?

Standard deductions are typically deducted from gross salaries and claimed as an exemption without proof of costs. They are flat deductions of ₹50,000 from your taxable salary that falls under gross wages. Since its advent, the standard deduction has provided numerous tax advantages to salaried people.

Also Read:- Income tax Allowances and Deductions Allowed in Salary | How To Save Income Tax For Salary Above 20 Lakhs?

Who is Eligible to Claim a Standard Deduction?

The standard deduction may be claimed through people receiving income and pension, excluding business owners. The standard deduction is not applicable in the following cases:-

  • Married people file one after the other if the partner itemized deductions.
  • Taxpayers with dual status or non-resident alien fame at some stage in a specific economic year.
  • Taxpayers submitting returns for a duration of less than a year.

The income Tax Return submitted for FY 2023-24 (AY 2024-25) has been started out. Remember, non-filing the ITR method notices and consequences. Avoid last-minute trouble by filing today and claiming maximum deductions.

Purpose of Standard Deduction

The purposes of introducing standard deduction are:

  • To reduce paperwork and allow for deductions regardless of the real costs.
  • To offer tax comfort to middle-class salaried individuals.
  • To offer benefits to pensioners.

Standard Deduction in New Tax Regime

The standard deduction under the New Regime is given below:

The Standard Deduction in the Old Tax Regime

Salaried individuals who’ve opted for the old tax regime can declare a standard deduction from their salary. They can claim a standard deduction of up to Rs 50,000 from their salary. Also, they could declare other deductions together with Section 80C, Section 80D, Section 80EE, Section 80G, and so on.

Must Read:- Deductions From House Property Income: Section 24 | Income Tax Slab Rates for AY 2024-25 | Calculate Your Income Tax Above 15 Lakh

Standard Deduction Limit on Salaried Employees in New vs Old Tax Regime?

The new tax regime is delivered in the budget of 2020, which permits concessional rates, but there are no exemptions or new deductions for salaried persons. The new regime has reduced the price of salary tax by as much as ₹15,00,000.

You have the option to choose among old or new regimes at the same time as submitting a return. Even pensioners can transfer among those alternatives.  

According to the new regime, it’s relevant if the taxpayer forgets deductions and exemptions below the following heads:-

  • Standard deduction of ₹ 50,000.
  • Deduction under phase 80C maximum up to ₹ 1,50,000.
  • Deduction under section 24 is a maximum of as much as ₹ 2,00,000.
  • Entertainment allowance and expert tax deduction under section 16(ii).
  • Leave travel allowance
  • House rent allowance
  • Premium of medical insurance between ₹ 25,000 to ₹ 50,000.
  • Interest in savings bills below section 80TTA up to ₹ 10,000.
  • Interest on savings bills for senior citizens under section 80 TTB up to ₹ 50,000. 

Standard Deduction – Union Budget 2018

Finance Minister Arun Jaitley delivered a standard deduction of Rs. 40,000 in Budget 2018. It replaced the delivery allowance of Rs. 19200 and medical reimbursement of Rs. 15,000 per annum.

Interestingly, the availability of Standard Deduction turned into advanced availability. However, it was abolished in the Finance Act 2005.

The preferred deduction is normally deducted from the gross salary and claimed as a deduction. This deduction may be claimed by all salaried employees regardless of category and need of any investment.

Also Read:- India Post GDS Salary in 2024 | RRB NTPC Station Master Salary 2024 | President of India Salary 2024

Standard Deduction – Interim Budget 2019

The Interim Budget offered on 1 February 2019 blanketed numerous tax benefits for the salaried and the middle class. Among them, a further amount of Rs.10,000 (improved from Rs.40,000) to the Standard Deduction is noteworthy.

With the Standard Deduction being Rs 50,000 now, it will help taxpayers immensely to reduce their tax return. Let us look at the given example and understand it:

Required documents for standard deduction

However, you need to have the following documents for standard deduction

  • Bank statements of the evaluation year
  • Statements for interest income
  • Tax Deducted at Source (TDS) certificates
  • Investment-related documents
  • Form 26AS and Form 1040

Conclusion

Salaried tax filers constitute the majority of the eighty million tax filers in India and need to cautiously overview and claim the exemptions and deductions available to them by right structuring of the remuneration, making eligible investments, and gratifying precise situations to optimize their tax deduction.

The alternative of whether or not to avail of a new tax regime by preceding certain exemptions/deductions also needs to be decided every financial year.

FAQ’s:-

1. Are standard deductions and rebates the same?

No. The standard deduction in Income Tax is offered under Section 16 and applies to salaried and pensioners. Rebate under Section 87A is available to all individual taxpayers, including self-employed, who have an annual taxable salary of less than Rs. 5 lakhs.

2. Are standard deductions of the Income Tax relevant to country and authorities employees?

Yes, the availability for standard deduction currently applies to all salaried people along with crucial and state government employees.

3. How do you say standard deductions if you are a salaried worker?

To claim the deduction benefit, you most effectively need to tell your company that you have selected the old tax regime. On the idea of those statistics, well-known deduction on salary may be applied routinely.

4. Can medical and transport allowances be claimed with standard deductions?

No. According to current guidelines, you can only declare a standard deduction on salary. Medical and transport allowances that had been available in advance can not be claimed.

Income Tax Allowances and Deductions Allowed in Salary Slip 2025

0
Income tax Allowances

Income tax is a tax that is levied on any person’s or company’s salary at some point in a financial year. It is immediately paid to the authorities, like all the other direct taxes. Provisions in the Income Tax Act 1961 also offer various Exemptions and Deductions under specific sections.

Deductions may be claimed against Investments, Allowances, etc, which could reduce the taxable amount of a person. Here we tell you about allowances and deductions.

Exemption of Income Tax Allowances

Exemption of Income tax Allowances

Income tax allowances are precise deductions that may reduce your taxable salary slip. The following are some of the most typically available income tax allowances in India.

1) House Rent Allowance

For salaried taxpayers, HRA is the primary salary with tax savings, the HRA received from the enterprise qualifies for exemption so long as the employee lives in a rented house and will pay rent to the proprietor. The HRA exemption can also be claimed by submitting evidence of rent paid to the business enterprise or at the time of submitting income tax returns under Sec 10(13A). The HRA amount exemption is less than.

  • HRA acquired from an agency
  • Actual rent paid much less than 10% of the basic monthly salary
  • 50% of the basic salary if the taxpayer is living in a metro town
  • 40% of the basic salary if the taxpayer is living in a non-metro town

Also Read:- How To Save Income Tax For Salary Above 20 Lakhs? | Calculate Your Income Tax Above 15 Lakh

2) Leave Travel Allowance (LTA)

Under the LTA, salaried taxpayers can declare costs incurred closer to home vacations which include the expense of travel tickets for themselves and their own family. The exemption doesn’t encompass expenses incurred for the whole trip, including buying, food fees, enjoyment, and entertainment, amongst others. This exemption may be claimed under Section 10(5) and is available most effectively for 2 travel in a block of four years.

The current block size started in January 2018 and results in December 2021. There is a provision to carry over one travel in case you didn’t claim it in a preceding block. So, in case you neglected to claim two tax exemptions over the past block of 2014-17, then you could carry over one experience to the new block that started in 2018. In this way, you may get most of 3 tax exemptions on LTA in a block of 4 years. However, as per Income tax regulations, delivery forward is authorized best whilst you make a declaration in the first year of the block.

3) Standard Deduction

For FY 2023-24, the limitation of the same old deduction is Rs. 50,000 for each of the old and the new regimes. As per Budget 2023, salaried taxpayers are actually eligible for a basic deduction of Rs.50,000 under the new tax regime also from the financial year 2023-24.

4) Medical Reimbursements

Employers often reimburse employees for medical charges incurred for themselves and their family individuals. Under Section 17(2) of the Income Tax Act, medical reimbursements of as much as ₹15,000 per annum are exempt from Tax.

5) Books, Periodicals

Employees frequently spend money on magazines, journals, books, newspapers, magazines, journals, and associated objects. As per income tax guidelines, employees have the possibility to receive reimbursement for these costs, that’s free from taxation.

6) Relocation Allowance

A Relocation allowance is given to undergo the relocation fees of the employees shifting from one place to another. Allowances may be claimed on various charges incurred together with travel fees, packaging costs, transportation of personal items, etc.

7) Children Education Allowance

Children’s Education Allowance is an allowance obtained by employees for the education of their children. The exemption limit for this allowance is INR 100 per month according to children, as much as most children.

 8) Salary From Gratuity

Gratuity benefits can be claimed by employees at the time of retirement or once they surrender after having worked for as a minimum 5 continuous years for the same agency. It is an economic praise from the employer or gratitude that they receive from the enterprise for rendering their service to the organization for a continuous period. Gratuity is calculated based on two elements – the employee’s last drawn salary and the number of years they’ve worked in the agency.

Must Read:- Income Tax Slab Rates for AY 2024-25 | How is Gratuity calculated in CTC? | SDM Salary in India

 Allowable Deductions

 Allowable Deductions

Income tax deductions are prices or investments that may be claimed as deductions from your basic salary. The following are some of the most basic available income tax deductions in India.

1) Section 80C

Section 80C is one of the most commonly used tax-saving options for people. Under this section, you may claim a deduction of as much as INR 1.5 lakh through making an investment in various units which includes Public Provident Fund (PPF), Equity Linked Savings Scheme (ELSS), National Pension Scheme (NPS), and many others.

2) Section 80D

This section gives income tax deductions for medical fees and medical insurance premiums. The most deduction that can be claimed under this by individuals under 60 years is up to INR 25,000, while senior residents can declare as much as INR 50,000.

3) Section 80C and Sector 24

Another key of this method is that it saves you from paying interest on a home loan. Homeowners have the option to claim as much as Rs.2 lakh as a deduction for interest on home loans for self-occupied property. If the residence property is let free, you may claim a deduction for the complete interest referring to this type of home loan. The loss from house assets that can be activated against other sources of salary has been limited to Rs.2 lakh.

In addition to the above, one can also claim the main issue of the housing loan reimbursement as a deduction under section 80C as much as a limit of Rs 1.5 lakh.

4) Section 80E

This section gives an income tax deduction for the interest you have paid on a loan taken for pursuing better training. The deduction is available for 8 years or till the interest is paid off, whichever is in advance.

5) Section 80G

This section gives income tax deductions for donations made to particular and prescribed charitable establishments and comfort budgets. The deduction varies based on the recipient company, so one needs to get a 50-100% tax credit score for the donated amount, without or with regulations.

6) Section 80TTA

This deduction may be claimed for interest earned on a financial savings bank account up to most of ₹10,000 in a financial year.

Also Read:- RRB NTPC Station Master Salary | President of India Salary | LIC ADO Salary

Tax Treatment on Notice Pay and Joining Bonus

Tax Treatment on Notice Pay and Joining Bonus

If an employee who has taken up a process under a bond or a settlement, leaves earlier than the stipulated duration; it can result in healing of notice pay from the employee or restoration of becoming a member of bonus. In a lot of instances, typically, these amounts are reimbursed by the new corporation. Let’s recognize the tax implications of these transactions.

1) Notice Pay

Ruhaan was hired by Super Ltd and needed to deliver an observation 3 months earlier than quitting his process. Ruhaan determined a totally interesting opportunity with Wonderful Ltd and decided to depart from Super Ltd without notice. Super Ltd made the restoration of notice pay from the total & very last settlement. Ruhaan wishes a TDS refund of the notice pay, given that he did not get hold of this salary.

If Incredible Ltd adjusts the total salary paid by the notice pay obtained and does not encompass this amount in Form 16 it problem for Ruhaan, he can take the TDS refund in his return. However, where the adjustment isn’t made by Super Ltd in the basic salary, the TDS deducted can be a loss for Ruhaan.

2) Joining Bonus

Aditya was running with AB Ltd and had signed a settlement now not to leave his task before the end of 6 months, and he was paid a Rs 50,000 joining bonus contingent on this. But Aditya quit AB Ltd and joined XY Ltd in four months. Aditya needed to now pay back the becoming a member bonus of Rs 50,000. Aditya asked his new organization, XY Ltd to reimburse him for becoming a member of the bonus.

Aditya needs to carefully have a look at the Form 16 from each of the employers, XY ltd will include becoming a member of bonus in its Form 16.

Conclusion

The Income Tax Act gives positive allowances and deductions available to salaried people. As a result, taxable salary and tax liabilities are decreased. However, it is extraordinarily essential to understand the individual and extent of those allowances and deductions to avail of them efficiently. They expect that the assesses need to incur positive costs while paying their salary. Deductions, then again, are available only if the assesses incur the applicable expenditure. The amount of tax legal responsibility can be notably reduced by availing of the various allowances and deductions available under the Income Tax Act. 

FAQ’s:-

1) What Are the Tax Deductions for Salary Slips?

This deduction that the corporation makes is what’s termed as Tax Deducted at Source or TDS. The percentage of TDS that desires to be deducted is determined by the salary of an employee and the income tax slab fee they come under and may range from 10% to 30%.

2) What Are the Allowances Allowed in Salary?

Basic salary, House rent allowance (HRA) Leave travel allowance (LTA) reimbursement.

3) What Is the Taxable Allowance in Salary Slips?

Taxable allowances talk over part of an employee’s salary that is taxable as per the Income Tax Act. An allowance implies a predetermined amount of cash a salaried employee gets from his organization to satisfy unique varieties of outlays out and beyond salary.

4) Is Income Tax Paid Allowed as a Deduction in Income Tax?

Any tax, responsibility, or price paid under any regulation in force is authorized as a deduction while it is paid- this consists of GST, customs duty, or every other Tax paid.

5) What Is a Special Allowance in Salary Slips?

Special allowance is given to the employees to compensate for their prices incurred even as performing their responsibilities or job. It is a set price that varies from one agency to every other whose information is stated actually on the employee’s salary slip and provided letter.

Recommended:-

1.Indian Navy Marcos Commando Salary
2.NSG Commando Salary
3.Sundar Pichai Salary
4.Air Aisa CEO Salary
5.Salary Slip Format in Excel

How To Save Income Tax For Salary Above 20 Lakhs?

0
How To Save Income Tax For Salary Above 20 Lakhs?

Taxes are a necessary part of the economy that works closer to the development and welfare of society. But we can not ignore the truth that higher tax prices can on occasion impose a financial burden on the taxpayers, mainly the high-salaried people.

Optimizing tax financial savings while adhering to salary tax legal guidelines is no less than mastering a complex art. If you earn above or around ₹20 lakhs in India, then the right tax planning and control could make a large distinction to your financial health, and if you want to Save Income Tax For Salary Above 20 Lakhs then read this article till the end.

The right news is, that there are some reliable methods to reduce your tax burden at the same time as per tax legal guidelines. In this blog, we can walk you through all those effective tax-saving ways and assist you in better tax planning for a 20 lakhs salary. Read on!

What are the Income Tax Slabs below the New Regime vs the Old Regime?

A taxpayer is required to calculate and pay taxes based on the slab to which he/she belongs. Given below are the slab rates under the new and old regimes

Also Read:- Calculate Your Income Tax Above 15 Lakh | Income Tax Slab Rates for AY 2024-25

Tax Saving Options Above 20 Lakhs Salary – New Tax Regime

Tax Saving Options Above 20 Lakhs Salary - New Tax Regime

The new tax regime gives lower and simplified tax fees however, it gets rid of most deductions and exemptions. Taxpayers opting for the new regime cannot claim deductions under sections consisting of 80C, 80D, 24(b), etc. While deductions are not allowed, taxpayers can declare the standard deduction and sure exemptions on particular allowances.

Tax Saving Options Above 20 Lakhs Salary – Old Tax Regime

The old tax regime follows the traditional salary tax slabs with various deductions and exemptions. Under the old regime, taxpayers can avail themselves of diverse tax exemptions and deductions under sections which include 80C, 80D, 24(b), etc. These deductions assist in reducing the taxable income, resulting in reduced tax liability. Taxpayers can declare House Rent Allowance (HRA), Leave Travel Allowance (LTA), and other allowances to reduce taxable income.

Old Tax Regime – Income Tax Slab Rates for FY 2024-25

Must Read:- How is Gratuity calculated in CTC? | How to Answer “What Are Your Salary Expectations?” | Content Writer Salary

Tax Calculation Under New and Old Regime

Tax Calculation Under New and Old Regime

Let us know the tax calculation for salary above 20 lakhs by example.

Example: Mr. A has a salary range of Rs 20 lakhs claiming deductions like HRA of Rs. 1,00,000, LTA of Rs. 20,000, Children’s education allowance for 2 children of Rs. 9,600, Professional tax of Rs 2,400. He claims deductions under 80C of Rs. A 1, 50,000, 80D – Medical coverage top rate of Rs. 25,000, and NPS contribution of Rs 50,000. Which is the satisfactory tax regime to opt for in this situation

How to Save Tax for Salary Above 20 Lakhs?

We already found out above that the right way to save taxes on salary slip is to avail most deductions to your taxable salary. Going with the same idea, the following table enlists the most variety of deductions that can be permissible and that you could declare during your Income Tax Returns (ITR) filing. Note that this case shares the deductions to be claimed for a worker filing ITR for FY 2023-24 for a CTC of as much as Rs. 2,00,000.

As can be seen from the table above, after claiming the most deductions within the ITR, the full taxable salary for the FY 2023-24 for a CTC of Rs. 20 lakhs comes to Rs. 4,50,000, that’s exempted from the tax rate under Section 87A of the Income Tax Act (falling inside the tax bracket under Rs. 5,00,000). Hence, the person with a CTC of 20 lakhs would need to pay 0 taxes or no taxes in this example.

Conclusion

Individuals earning a salary above ₹20 lakhs can make the most of those tax-saving options to lessen their tax legal responsibility. However, it’s important to note that the tax legal guidelines are tough to share, and it’s beneficial to consult a tax expert to ensure that you are availing of the tax benefits in a compliant manner.

Saving tax on a salary above 20 lakhs in India isn’t always impossible in case you plan your finances accurately and employ the various tax-saving options available. By deciding on the right tax regime, investing in tax-saving contraptions, buying health insurance, claiming HRA exemption, claiming other allowances and reimbursements, and making an investment in NPS, you can reduce your tax legal responsibility substantially and keep more money to your future goals.

FAQ’s:-

How do you save income tax on a salary above 15 lakhs?

If your taxable salary is as much as Rs. 15 lakhs, you could claim tax deductions really worth Rs. 10,000 at the interest earned on your savings bank account. This is according to Section 80TTA of the Income Tax Act.

What is the tax on a 20 lakh salary?

A tax of Rs. 3,51,000 is levied on a gross salary of Rs. 20,00,000 according to the new tax regime.

What is the tax on a 20 lakh salary?

A tax of Rs. 3,51,000 is levied on a gross salary of Rs. 20,00,000 according to the new tax regime.

Deductions From House Property Income: Section 24

0
Deductions From House Property Income-Section 24

India has been witnessing continuous and fast increases during recent decades. It is the imagination and prescient of the United States to be a developed state by the 100th year of Independence. Affordable housing for all is one of the critical things in the development process of the country. The government acknowledges this need and consequently, they have provided you with several key advantages to supply relief by tax breaks under section 24 of the Income Tax Act.

Income from House Property

There are some cases wherein Income from a house property can occur:-

  • Housing income by rent
  • The annual cost of the property which is considered “deemed to be set free” for income tax purposes (This occurs when we very own more than one property)
  • The annual cost of the property which is self-occupied

The Gross Annual Value differs in all 3 cases, as shown below:-

Also Read:- Calculate Your Income Tax Above 15 Lakh | Income Tax Slab Rates for AY 2024-25 | How is Gratuity calculated in CTC?

Deductions Under House Property

Deductions Under House Property

The deductions made under house property are given below

  • Municipal tax deduction

The annual amount paid to the municipal company of the place is the municipal tax. These taxes are to be deducted from the gross annual fee to get the total value of the house assets. Deduction on municipal tax is granted if it is borne by the house proprietor and paid during that economic year.

  • Standard deduction

30% of the annual cost calculated is a standard deduction. This is authorized when your expenditure on the belongings is increased or decreased as well. It is irrespective of the expenditure which you incur on insurance, strength, maintenance, water supply, and many others. 

  • Deduction of interest on house loan for belongings

Homeowners get to assert a deduction of as much as ₹2 lakh on the home loan interest if their family lives in those belongings. The same is implemented whilst the house is vacant. In case you set free the property on rent, the entire interest on the home loan is permitted as a deduction.

Who Can Claim Deductions Below Section 24?

Who Can Claim Deductions Below Section 24?

Individuals owning residential belongings that generate rental Income or are self-occupied are eligible to claim deductions below Section 24.

Types of Deductions

  • Standard deduction: A flat 30% deduction is authorized on the gross annual price of the belongings, regardless of any real costs incurred. This makes it problem-free and accessible.
  • Interest on home loan: If you have availed a loan for the purchase, construction, or restoration of the belongings, you could claim the interest paid on the loan as much as Rs. 2 lakhs per year.

Must Read:- SDM Salary in India | Content Writer Salary in India | President of India Salary

Calculating the gross annual price

The gross annual cost is the honest rental Income the assets need to fetch if rented out in its current situation. It may be calculated as:

  • Real rent received: If the assets are rented out, the real rent acquired is taken into consideration as the gross annual cost.
  • Municipal valuation: If there are self-occupied assets, then municipal valuation is used for gross annual income.

Pre Construction Interest

An advantage of pre-construction interest arises when you take a home loan for buying or construction. Two critical factors so that it will not be forgotten earlier than claiming this interest are:-

  • It cannot be claimed for a loan taken for maintenance or reconstruction of the house;
  • The pre-construction and interest on housing loans that can be claimed for a specific year cannot exceed Rs 2 lakhs.
  • Also, it would be exceptional if you remembered that the interest is authorized in 5 same installments starting from the year the house is bought or the construction is completed.

If the construction of our home gets finished on 15 September 2022 (FY 2022-23), then we are eligible to assert a deduction accruing to at least 1/5th of the interest paid until 31 March while submitting tax returns.

Conditions for Claiming Interest on Home Loan

Conditions for Claiming Interest on Home Loan

To be eligible for this deduction, you shall fulfill the three requirements mentioned below.

  • After 1 April 1999, the purchase or construction for which the loan was received.
  • The acquisition or creation is finished in 5 years (3 years till FY 2015–16) following the end of the fiscal year wherein the loan became taken.
  • For loan, an interest certificate is accessible. Your interest deduction may be confined to Rs. 30,000 if one or more of these conditions is real.
  1. The real property was bought, built, repaired, or rebuilt with the loan before 1 April 1999.
  2. The loan is received on or after 1 April 1999 and is hired to purchase, construct, renovate, or rehabilitate real property for a house.

Computation of Income Under House Property

Say, someone repays a housing loan of Rs 4 lakh yearly out of which Rs 2 lakh is the interest component. He is earning Rs 7000 monthly from permit-out belongings and also pays municipal taxes of Rs 3000 for the house. Let’s calculate his Income from the home property in both the eventualities: (1) He has a self-occupied property, or (2) The assets are rented out.

Remember, the most loss set-off allowed in a financial year is set to Rs 2 lakh. The final loss may be carried forward to future years – 8 years overall. However, in those 8 years, it can only be sparked off from Income from house assets.

Conclusion

Understanding the details of Section 24 of the Income Tax Act can help you make smarter tax decisions for Income from house property. If you’re a homeowner or planning to buy a home, clarity on deductions, gross annual value, and the net annual cost of house property is crucial to avoid tax discrepancies. 

What is money.rumusrumus.com: A Deep Dive into

0
money.rumusrumus.com

In the cutting-edge world, where money is becoming more precious, making plans makes sense. If you share the same opinion, Money.Rumusrumus.Com will become a great option. You may also be surprised, why? It is based on the idea that this level involves taking recommendations and mendacity to get money. It covers strategies for each person and company so as to always maintain your wallet completely. Read more to know about the Money.Rumusrumus.Com, its features, benefits, etc.

About Money.Rumusrumus.Com

Money.Rumusrumus.Com is an extremely good platform that works as a guide to all of the customers. It provides various information and strategies that allow the users to make their financial strategies. It will calculate all your expenses according to your income and can tell how a whole lot could be spent. Moreover, it’ll also provide you with the bring about one of these ways so that you can also make financial savings.

Keeping all of the prices, income, and financial savings in mind. It also recommends some right source of income in which the person can make investments and may earn cash aside from their income, something their main source of income is. This platform affords quite a few tools so the entirety can be planned in a better way.

Also Read:- Sportsgurupro.com Task Offers | 4 steps to improve your Project Management skills | President of India Salary

Money.Rumusrumus.Com – Maximising Financial Growth

While saving is important for short-term financial security, investing holds the key to unlocking long-term wealth and financial increase. However, navigating the world of investments is daunting without adequate knowledge and steering.

Herein, the significance of Money.Rumusrumus.Com in demystifying the complexities of investing.

Through comprehensive educational resources and interactive active power. Here, individuals can gain insights into various investment paths. Also ranging from shares and bonds to real estate and mutual investment.

Why choose money.Rumusrumus.Com?

With endless economic websites vying for your interest, you might be thinking: why should I choose money.Rumusrumus.Com? Well, for starters, this platform stands out for its dedication to delivering top-notch, actionable content that yields actual outcomes. Unlike other sites that bombard you with fluff and filler, money.Rumusrumus.Com cuts through the noise to offer you sensible insights that you could put in force right away.

  • Expert Insights: Gain access to expert analysis and insights from expert economic professionals.
  • Actionable Strategies: Discover demonstrated strategies for constructing wealth, investing accurately, and attaining financial independence.
  • Interactive Tools: Utilise interactive tools and calculators to evaluate your financial health and track your development.
  • Community Support: Connect with like-minded individuals and share your experiences, tips, and achievement stories.

Benefits of the use of money.Rumusrums.Com

Benefits of the use of money.Rumusrums.Com

The benefits possible by using the Money Rumus platform are given below:-

  • Financial Planning: The platform is designed to enable customers to increase and enforce financial decisions. Whether it’s personal financial savings, investing, or debt management.
  • Educational Resources: This is more valuable. Here, you can actually discover educational content. It is to help us examine diverse financial ideas and make appropriate financial choices.
  • Accessibility: The online portal Money.Rumusrumus.Com is accessible everywhere. A big gain for customers is they can get access to it at any time and manage their finances online.

Must Read:- India Post GDS Salary | RRB NTPC Station Master Salary | Data Entry Operator Salary

What Can You Expect from Money.Rumusrumus.Com?

Money.Rumusrumus.Com gives a wide variety of topics related to personal finance. From fundamental standards consisting of expert credit scores and creating a financial plan to more advanced subjects like real estate investment and retirement making plans – the website covers all components of cash management in a smooth-to-recognize way.

The platform also features articles written by specialists in the area who offer valuable insights based on their own stories. This permits readers to benefit from expertise from specialists who have already performed financial success.

Moreover, Money.Rumusrumus.Com frequently updates its content with cutting-edge trends and adjustments in the financial system so that site visitors can stay up to date with the current data in the financial world.

Effective Investment Strategies For Achieving Financial Goals

Saving can be a great option for the future, however, it’s going to simplest be for a short period of time. You need to begin investing for future goals. But most effective few people know the right knowledge about investment. So, cash.Rumusrumus.Com offers a few sources and tools to help you in better investment. By this you can get a guide and you will be capable of addressing the risk by the point.

  • Discipline And Planning: To gain financial dreams, you need to follow some factors. These factors include area and making plans. You can also get provided tools and data. Also helps to build a network for users to proportion insights, examine from each different, and get help. So Users can learn about risk tolerance, investment desires, and diversifying their portfolios. This may help them to make smart decisions.
  • Financial Planning: The platform offers educational content on financial making plans, retirement techniques, and wealth control. Users can take care of their finances confidently and be ready for any challenges, using this information and these tools.

Also Read:- LIC ADO Salary | Civil Engineer Salary | Game Developer Salary

Time Period Investment: Money.Rumusrumus.Com

This platform will ask you and guide you to invest in different things which are more reliable at that point. So that you can make income and the risk of loss needs to be below than minimum. This investment does not offer you the loss but it is the aspect which prohibits the character from the useless fee and invest it at the right place. Not only this however, those investments will supply a good profit and it’s a long time investment. Long term investment is very important because after a point of time a phase comes into all lifestyles.

This section asks for more money as in this age the person grows to be older and then the children come to be younger. So at that time these investments work as a boon into the life of the person who invests their cash at the right location at the right time. For the quick time period also it facilitates in the diverse methods as it shows you the entire investment plan from wherein you’ll get to know that the way to manage costs and those small financial savings permit you to with the cutting-edge essential prices.

Conclusion

Money.Rumusrumus. Com is a valuable device for managing your finances. It affords insightful investment advice, widespread financial planning tools, and academic content. Users can optimise their financial techniques. They can work to maximise their wealth by debt control strategies, investment steerage, and funding tools.

Calculate Your Income Tax Above 15 Lakh and How to Save it

0
Income Tax Above 15 Lakh

Finance Minister Nirmala Sitharaman introduced the new tax regime in Budget 2020 giving taxpayers the option to pick out between it and the existing tax structure once they file their taxes. At the same time, your salary may be taxed at lower rates as per the new tax slab. You will not be able to use the deductions under the Income Tax Act in advance, and Income Tax Above 15 Lakh to lower your tax liability in addition.

As per authorities estimates, 5.3 crore taxpayers out of a total of 5.78 crores declare tax exemptions amounting to less than Rs 2 lakh. The most famous of those include investments in the Public Provident Fund, lifestyle coverage plans, tax-saving deposits, and many others most of which fall under the Rs 1.5 lakh most limit given as per Section 80C.

New Tax Regime Slabs as per Union Budget 2023

Individuals pay taxes on their annual salary based totally on the tax slab changes proposed in the Finance Bill at some stage in the price range session. However, the Union Budget 2023 provided the taxpayers with an option u/ Sec 115 BAC of the IT Act, 1961, to choose between salary tax slab prices with varying approaches.

Refer to the table under to check old vs. New tax slabs and the most salary tax applicable with no tax exemptions and deductions for the respective tax slabs

Also Read:- Income Tax Slab Rates for AY 2024-25 | How is Gratuity calculated in CTC? | Income Tax Slab and Rates for FY 2023-24

Old Income Tax Slab Structure(FY 2021-22)

New Income Tax Slab Structure(FY 2022-23)

How to Save Tax for Salary above 15 Lakhs?

Here are steps to follow to save tax for a salary above 15 lakhs

  1. Utilize Section 80C deductions: Invest in tax-saving contraptions including EPF, PPF, NSC, and ELSS to assert deductions as much as Rs. 1.5 lakh under Section 80C.
  2. Maximize home loan benefits: If you’ve got a home loan, ensure you declare deductions on each important and interest payment under Sections 80C and 24(b), respectively.
  3. National Pension Scheme (NPS): Contribute to NPS to avail more deductions under Section 80CCD(1B) up to Rs. 50,000.
  4. Health coverage charges: Invest in a comprehensive medical insurance policy for yourself and your circle of relatives to claim deductions under Section 80D.
  5. Optimise expert tax and well-known deduction: Deduct the professional tax paid and declare the standard deduction of Rs. 50,000 available for salaried people.
  6. Utilise HRA and LTA: If you’re a tenant, claim House Rent Allowance (HRA) based on rent paid. Additionally, utilize Leave Travel Allowance (LTA) for tax-free journey expenses.
  7. Explore tax-exempt allowances: Leverage allowances like conveyance allowance, phone, and medical reimbursements in the exempt limits to maximize tax financial savings.
  8. Invest in tax-saving fixed deposits: Consider tax-saving constant deposits with a lock-in period of 5 years, offering deductions under Section 80C.

Tax Savings Under New Tax Regime

Following deductions are available under the new tax regime when you have a salary of more than 15 lakhs

  • For salaried individuals – Deductions up to Rs 50,000
  • Section 80CCD(2) – Employer contribution to NPS
  • Section 80 CCH
  • Section 57(iia) – Family Pension obtained.
  • Exemption on voluntary retirement 10(10C), gratuity u.S.10(10) and Leave encashment u.S.A.10(10AA)
  • Interest on Home Loan on the permit-out assets (Section 24)
  • Transport allowances in case of a differently-abled individual.
  • Conveyance allowance acquired to meet the conveyance expenditure incurred as part of the employment.
  • Any repayment received to satisfy the cost of travel on tour or transfer.

Income Tax Exemptions under Old Tax Regime

Save Rs.1.5 Lakhs to your Taxable Income under Sections 80C, 80CCC, and 80CCD

  1. Financial Protection Instruments
  • Term Insurance
  • Life Insurance
  1. Retirement and Long-Term Objectives
  1. Investment for Child’s Future:
  • Sukanya Samriddhi Scheme (SSS)
  • Child Plans from Insurance Providers
  1. Wealth Protection
  • National Savings Certificate (NSC)
  • Tax Saving Deposits – 5 Year
  • Life Insurance endowment and Money-again plans

Income tax above 15 lakh for salary

An additional tax benefit is available for contributions of up to Rs 50,000 to the National Pension Scheme as per 80CCD (1B) provisions taking the overall to Rs 2 lakh. Income tax above 15 lakh However, if you fall in the higher tax bracket and are searching for tax savings for a salary above Rs.15 lakhs as you get prepared to fill your income tax go back for FY 2019-20, here are a few things to keep in mind.

If you do not put money into tax-saving system

In her finances speech, the Finance Minister explicitly stated that a person with an annual income of Rs 15 lakh not availing any deductions as per the proposed tax structure would have to pay the most effective Rs 1.95 lakh as a tax rather than Rs 2.73 lakhs in the old regime. To obtain this, you have to allow the pass of tax benefits under Chapter VI A of the Income Tax rules as well as the same old deduction of Rs 50 000 for FY 2019-20.

If you make investments up to a minimum of 1.5 lakh

If you’ve got invested in a Public Provident Fund, Employees Provident Fund, Sukanya Samriddhi Scheme, life coverage or medical insurance top class, tax-saving fixed deposits from banks or post offices, or every other provision that allows tax exemption to the track of Rs 1.5 lakh, you would still stand to lose Rs 31,200 in tax saving for salary above 15 lakhs by following the old regime tax paying technique.

If you avail deductions worth 2.5 lakh or more

If your annual salary is between 15 lakhs to 20 lakhs and you declare tax deductions worth 2.5 lakhs, you have the option to pick between both of the 2 regimes for the reason that the tax payable might be more or much less the same. However, in case you are focused on tax saving for a salary above 15 lakhs and the amount of exemption in tax sought by you is more than 2.5 lakhs, it’s far more prudent to stick to the old technique of tax computation. Let us understand this by looking at tax computation by each method for someone drawing a yearly salary of Rs 20 lakhs.

Tax Calculation for Annual Income of 20 Lakhs – Old Regime vs New Regime

Conclusion

In the Indian taxation device, a salary above 15 lakhs needs a nuanced approach. Understanding tax slabs, leveraging exemptions, and judiciously selecting among regime slabs are the bedrock of efficient plans. Exploring investment ways like PF, ELSS, and NPS under Section 80C can bolster financial savings.

Additionally, maximizing deductions and thinking about long-term period capital gains techniques in addition to high-quality procedure. By using those strategies, people can optimize their tax savings and steady their economic future.

FAQ’s:-

1. How much tax do I have to pay for 15 lakhs?

You will pay 0 tax on a salary of 15 lakhs, given you have invested in tax savings options and declared applicable deductions and exemptions. Under the old regime, your net tax payable may be 0 in case you declare exemptions and invest in tax-saving schemes.

2. How to pay 0 tax for income up to 10 lakhs?

To pay 0 tax for a salary up to 10 lakhs, you have to follow the old tax regime. Furthermore, you ought to take advantage of all the tax exemptions and invest in tax savings schemes that qualify for deductions for paying zero tax.

3. Can you save 100% on tax?

Yes, with proper tax planning, it is possible to save 100% on tax. To save on tax, you need to spend money on tax-saving alternatives and also declare for all applicable exemptions.

4. How much is the salary tax-free per the Income Tax Act?

Income as much as INR 2,50,000 is tax-free. However, the Finance minister has multiplied the restriction in the cost range of 2023. Now, under the new tax regime, a salary up to INR 3,00,000 is tax-free.

Income Tax Slab Rates for AY 2024-25

0
Income Tax Slab Rates for AY 2024-25

In India, income tax is based on the income tax slabs and costs, which are determined each year. The income tax slabs are distinct under old and new tax regimes. For this year, from April, the income tax slab implemented for the financial year may be 2024-25, and the assessment year will be 2025-26.

Based on new income tax slab structures, exceptional tax rates are applied to salary stages. When there’s a growth in salary, the tax fee also increases. Income tax is set by the authorities’ salary tax department.

What is an Income Tax Slab?

An income tax slab is a hard and fast income stage that might be taxed at a set rate set by the government. The income tax slab in India determines how much tax an individual needs to pay based on their taxable income. The government revises the income tax slabs on a daily basis to account for changes in inflation and the cost of living.

The income tax slabs are divided into different categories, which include individual taxpayers, Hindu Undivided Families (HUFs), corporations, and corporations. Different tax rates are observed for different levels of taxable salary in each class, with higher costs applied to higher levels of income.

Also Read:- Income Tax Slab and Rates for FY 2023-24 | How to Calculate Income Tax For Salaried Persons

New Income Tax Slabs For FY 2024-25

In response to the Union Budget 2023, good-sized amendments were made to the salary slip tax structure under the new tax regime for the financial year 2023-24, applicable from Assessment Year 2024-25. A notable amendment in the income tax slabs 24-25 consists of the discount of tax slabs from 6 to 5, along with an increase in the basic exemption limit from Rs. 2.5 lakh to Rs. 3 lakh. These changes, effective from 1 April 2023, aim to simplify the tax-paying way and provide relief to taxpayers.

Income Tax Slabs Under New Tax Regime for FY 2023-24, FY 2024-25

Range of IncomeTax Rate
Up to Rs. 3,00,000Nil
Rs. 3,00,001 to Rs. 6,00,0005%
Rs. 6,00,001 to Rs. 9,00,00010%
Rs. 9,00,001 to Rs. 12,00,00015%
Rs. 12,00,001 to Rs. 15,00,00020%
Above Rs. 15,00,0030%

Income Tax Slabs For the Old Tax Regime

For the old tax regime, here is information on income tax slabs-

Old Tax Regime SlabsIndividuals
(Age < 60 years)Resident Senior Citizens
(More than 60 but less than 80 years)Resident Super Senior Citizens
(80 years and above) Individuals
Old Tax Regime SlabsIndividuals
Upto Rs 2,50,000NilNilNil
Rs 2,50,001 to Rs 3,00,0005%NilNil
Rs 3,00,001 to Rs Rs 5,00,0005%5%Nil
Rs 5,00,001 to Rs 10,00,00020%20%20%
Above Rs 10,00,00030%30%30%

Old Tax Regime Vs New Tax Regime for FY 2024-25

The advent of the new tax regime in the 2020 Budget, with similar amendments in 2023, has stirred big discussions amongst taxpayers. Comparing the old and new tax regimes facilitates in knowledge which option may be more useful based totally on personal economic conditions and choices.

New Tax Regime

The new tax regime, effective from 1 April 2020, reduces tax charges for higher incomes compared to the old regime, aiming to reduce tax liability under positive conditions. This regime is optional.

Old Tax Regime

Under the old regime, taxpayers have the option to claim over 70 different tax deductions and exemptions, inclusive of the ones under Section 80C, HRA, LTA, etc., to minimise taxable income.

Comparing the Tax Rates of the Old Tax Regime and the New Tax Regime

Here is a tabular of the tax fees throughout the old tax regime for FY 2023-24 (AY 2024-25), the new tax regime earlier than Budget 2023 (until 31 March 2023), and the new tax regime after Budget 2023 (applicable from 1 April 2023):

Income Range        Old Tax RegimeNew Tax Regime (Before Budget 2023)New Tax Regime (After Budget 2023)
Rs. 0 – Rs. 2,50,000NilNilNil
Rs. 2,50,001 – Rs. 3,00,0005%5%Nil
Rs. 3,00,001 – Rs. 5,00,0005%5%5%
Rs. 5,00,001 – Rs. 6,00,00020%10%5%
Rs. 6,00,001 – Rs. 7,50,00020%10%10%
Rs. 7,50,001 – Rs. 9,00,00020%15%10%
Rs. 9,00,001 – Rs. 10,00,00020%15%15%
Rs. 10,00,001 – Rs. 12,00,00030%20%15%
Rs. 12,00,001 – Rs. 12,50,00030%20%20%
Rs. 12,50,001 – Rs. 15,00,00030%25%20%
More than Rs. 15,00,00030%30%30%

Must Read:- How is Gratuity calculated in CTC? | How to Answer “What Are Your Salary Expectations?” | How to Calculate Gratuity

Conditions for Opting for the New Tax Regime

The taxpayers who’ve opted for the new regime will have a tendency to forgo a few deductions and exemptions that might be available in the old regime of taxation. Some of the common deductions & exemptions not allowed under the new regime are-

Exemptions/Deductions unavailable under the FY 24-25 new tax regime?

The 2020 cost range has eliminated about 70 of the exemptions available under the new regime. The following exemptions and deductions are a number of the most important ones that might not be available if the new tax regime slab is selected for tax calculation –

  • House Rent Allowance under Section 10 (13A)
  • Leave Travel Allowance under Section 10(5)
  • Allowances underneath Section 10(14)
  • Food coupons and different tax-free allowances and perquisites
  • Deductions under Chapter VI A of the Income Tax Act like Section 80C, 80D, 80TTA, and so forth.
  • Deduction for home loan interest paid for self-owned house property under Sections 24 (b) and Section 80 EEA

Exemptions/Deductions are Available under the FY 24-25 New Tax Regime?

Under the new income tax brackets 24-25, taxpayers can nevertheless avail of deductions and exemptions, no matter the removal of many previously available ones. These consist

  • NPS Contributions by Employer: Contributions to the National Pension System (NPS) through a business enterprise, up to 10% of the income of the worker (and 14% for Central Government employees), are deductible under Section 80CCD(2).
  • Standard Deduction on Rental Income: For rented-out belongings, a well known deduction of 30% of the net salary is authorised, simplifying the calculation of taxable salary from house property.
  • Home Loan Interest: Interest paid on a home loan for a permit-out property can be deducted from the income earned, although a loss from residence assets can’t be offset towards other salary heads.
  • Transport Allowance for Divyang Employees: Divyang (disabled) employees are eligible for a delivery allowance exemption to cover daily tour charges between their place of work and home.
  • Conveyance Allowance: Expenses incurred on conveyance for reputable duties are permissible as a conveyance allowance.
  • Allowances for Travel and Transfer: Allowances given to employees for the costs related to tour or transfer are exempt.
  • Daily Allowance: A daily allowance received to cover daily costs even as far from the normal location of duty is also allowed. 

How to Calculate Income Tax for Income Tax Slabs for FY 24-25

To illustrate the technique of salary tax calculation, please do not forget the state of affairs of Anjali, a salaried person with an annual salary of Rs. 9,00,000. Anjali is entitled to deductions beneath Section 80C amounting to Rs. 2,00,000.

Firstly, Anjali determines her gross taxable income by subtracting the deductions from her total salary. This calculation is as follows: Rs. 9,00,000 (total salary) minus Rs. 2,00,000 (deductions), resulting in a gross taxable salary of Rs. 7,00,000. Next, we investigate the applicable tax slabs that are based hence:

  • Up to Rs. 2,50,000: 0% tax
  • Rs. 2,50,001 to Rs. 5,00,000: 5% tax
  • Rs. 5,00,001 to Rs. 10,00,000: 20% tax
  • Above Rs. 10,00,000: 30% tax

Given that Anjali’s income falls in the Rs. 5,00,001 to Rs. 10,00,000 range, the relevant tax cost for her is 20%.

To compute the tax payable, we calculate the salary that falls in this slab (Rs. 7,00,000 – Rs. 5,00,000) and apply the 20% tax rate. Accordingly, the tax amount for Anjali in this slab is Rs. 40,000. Regarding the surcharge, Anjali now does not need to trouble herself, as surcharges are levied on earnings exceeding Rs. 50 lakhs and her income does not attain this threshold. Thus, for the financial year 2023-24, Anjali’s total income tax legal responsibility amounts to Rs. 40,000.

Conclusion

The income tax slab rate in India has gone through big modifications over the last few years. By introducing current changes with the Income Tax slabs for FY 2023-24, the government is making an attempt to simplify the ordinary tax system for all people and agencies.

Sportsgurupro.com Task Offers

0
sportsgurupro.com task offers

With the demand for smartphones and the net, there’s been an expansion in the number of systems catering to sports fans. Remember the days when playing sports meant going to a field or court? Those days are long gone. Digital platforms have transformed the way we view, follow, or even play sports. So, where does Sportsgurupro.Com fit into this landscape? In today’s digital age, this couldn’t be more accurate, particularly in relation to sports activities platforms. Among these, the 1xbet online betting sports site stands out, offering a comprehensive experience for sports enthusiasts. So, let’s dive deep into one such platform that’s making waves – Sportsgurupro.Com undertaking.

What is Sportsgurupro.Com?

Sportsgurupro.Com is a famous and revolutionary platform that connects sports enthusiasts with numerous possibilities to earn cash. It is essentially a market for completing tasks related to sports, along with writing articles, developing social media content, providing education or evaluation services, and more.

The platform was created with the intention of empowering individuals who have an ardour for sports and want to show it into a give of profits. Whether you’re seeking to make some more money on the aspect or hoping to build a complete-time profession in the sports activities enterprise, Sportsgurupro.Com gives several options for achieving your economic needs.

Portsgurupro.Com has an extensive range of undertaking categories. From writing and design tasks to training and consulting possibilities, there is something for everyone on this platform. This range not only permits you to pick out responsibilities that align with your pursuits and strengths but also gives you the chance to discover the best areas in the sports activities industry.

Also Read:- 4 steps to improve your Project Management skills | Content Writer Salary in India | India Post GDS Salary

Sportsgurupro.Com Task Offers!

Here are the various Codes offered by sportsgurupro.com task offers

  • 99LWTLU90N6CKHED
  • 8FG8G3DH08W22EJG
  • FVMGK8STWVBG9AXP
  • 2RN5E8SWJY7AAPFY
  • 6ZG0GXCECKCB7E87
  • 73BXZSKL9KR98ZWK
  • 9BDP39HW32CPEDMW
  • CHWUVRP2F535FJRU
  • JSPV11952JW5U02J
  • GL74BAKRXPETALE5
  • C667HKXM0WUT1WKJ
  • JRF55LDRH7LE8Y5D
  • AZRGBGYUGLG2GEAN

Features of Sportsgurupro.Com Task Offers

Though there are many features which the Sportsgurupro.Com task gives, knowing them intensively permits you to do lots better.

  • Intuitive Design: This platform is made with a focus on user consolation. This guarantees that any new consumer coming on the platform can use it with no confusion.
  • Easy Navigation: Layout is easy and ordered, meaning customers can find the section they need to go in. So, it could save time and decrease the frustration resulting from complicated systems.
  • Quick Access: All the capabilities are easy to get access to at once from the main dashboard. Users can manage the sports easily.
  • Personalized Task: It gives responsibilities based on your own dreams and experience level. This approach to every mission is vital for your education. This could make your education higher and more smooth.
  • Adaptive Advice: The platform updates your tasks to maintain them challenging, as you get better. This facilitates you to stay engaged and maintain improvement. It could help you reach your goals quicker.

How Do Task Offers Work?

Sportsgurupro.Com tasks are essentially quick-term projects that you may complete in trade for cost. These tasks can range from writing blog posts, growing social media content, and studying sports statistics, to providing predictions on upcoming games. Here’s a breakdown of how you could get began:

  • Sign Up and Create a Profile: Begin by signing up on Sportsgurupro.Com and growing a detailed profile that highlights your sports activities information and skills.
  • Browse Task Offers: Once your profile is created, you may browse through the available venture offers. The tasks are categorized through sports, type of work, and fee amount.
  • Apply for Tasks: Apply for the tasks that healthy your understanding and interest. Ensure to tailor your application to exhibit why you’re satisfactory for the project.
  • Complete the Task: After completing, schedule the task at a unique time.
  • Get Paid: Upon a hit of entirety and approval of your task, you’ll receive payment by the platform.

Must Read:- RRB NTPC Station Master Salary | President of India Salary | Interactive Marketing Report

How to login in to the Sports Guru application

It is very easy to log in to the Sports Guru app. For this, the user needs to type in the username and password at the sports guru’s site; if the player does not have a username and password, then the player needs to sign in.

For this, the username is to go to the SportsGuru website, and here, the player needs to press the sign-in option and enter some info like name, username, email ID, password, and many others. The player will successfully complete their application after completing the procedure.

Tips for Boosting Your Earnings

To make the most out of Sportsgurupro.Com undertaking, right here are a few tips based on experience:

  • Stay Active: Regularly check the platform for new task offers. The more active you are, the higher your chances of securing tasks.
  • Deliver Quality Work: Always intention to deliver splendid work. This not only ensures you receive a commission however also increases your chances of being selected for future tasks.
  • Expand Your Knowledge: Keep up with the current sports activities information and tendencies. The more informed you are, the more valuable your contributions will be.
  • Build a Strong Profile: A detailed and expert profile can entice more undertaking offers. Highlight your capabilities, experience, and ardor for sports activities.

Conclusion

Here you have learnt about Sportsgurupro.Com. It conducts special activities and prizes. Users can comply with the regulations and win like iPhones. The platform is easy to apply and might provide personalized services to help improve your abilities. You earn points for finished tasks, and you may use these factors to earn rewards. Stay active and offer the best service to get the most out of these offers. Visit the reliable website for more details and to enroll in the promotions. Follow the easy steps to win interesting prizes and rewards. But don’t forget the game is all about good fortune and fate. 

How is Gratuity calculated in CTC?

0
How is Gratuity calculated in CTC

A financial bonus that is regularly ignored yet has a large impact on an employee’s total salary is the Gratuity. The complexities of gratuity calculations are probably complicated, no matter their importance. In terms of CTC (Cost to Company), we talk about the topic of Gratuity in this article and tell you how Gratuity is calculated in CTC. So, keep reading this article to learn about Gratuity and its calculation in CTC.

What Is Gratuity?

The term refers to the amount that an organization will pay his employee, in return for services provided by him to the agency. However, employees who have been hired by the Employer for 5 years or more receive the gratuity amount.

Also Read:- How to Calculate Gratuity for Private Employees | How to Calculate Gratuity for Government Employees

How Do Gratuity Payments Work?

The company will salary the gratuity amounts out of their own pocket or buy a regular gratuity coverage plan from a service issuer. The company then will make annual payments to the employees, and the coverage employer, in return, will pay the employee the gratuity amount if the policy policies and regulations are followed. The organization’s salary is the complete gratuity sum without any contributions from the employee.

Regardless of the various years of non-stop employment, the regulation required that the organizations salary the Gratuity to the employee or their nominee if the employee was handicapped or died. The regulation, in addition, states that if the nominee is a minor, the assistant work commissioner needs to deposit the finances in the minor’s name in a time period deposit with a nationalized bank till the minor reaches the age of majority.

Eligibility Rules for Gratuity Payment – Employees

Any person satisfying the following eligibility criteria is eligible to acquire Gratuity under the Payment of Gratuity Act, 1972

  • The person has to be eligible for superannuation.
  • The person must have resigned after rendering a minimum of 5 years of non-stop employment in the same organization.
  • According to Section 4 of the Gratuity Act, in case of termination of service due to loss of life or incapacity, an exception is made to the 5-year non-stop service standards.
  • Furthermore, if an employee dies in harness, the beneficiary or nominee is taken into consideration for gratuity payment.

Eligibility Rules for Gratuity Payment – Organizations

Following are the organizations that fall under the Payment of Gratuity Act of 1972 to receive gratuity payments

  • Organizations employing 10 or more employees
  • Every company having 10 or more employees
  • Every shop or established order employing 10 or more people on any day of the previous year (particular by the State Government or Central Government)
  • Every organization concerned with the Gratuity Act whose employees are less than 10 are considered eligible.

How to Calculate the Gratuity Amount In CTC?

An organization can express gratitude to employees in diverse methods for their extraordinary service and hard work throughout their employment. Giving away gratuity payments is one such perk given to the employees.

Gratuity can only be withdrawn after working for 5 years at the time of leaving or retirement. People used to refer to gratuity amounts or calculations in various countries. The Act stipulates that Gratuity be paid at 15 days’ wages for each year of service finished, as much as a maximum of ₹10 lakh. Gratuity is paid at 7 days’ salary for every season in an establishment.

Gratuity is computed as 4.81 percent of basic salary under the Payment of Gratuity Act 1972. Here is the basic gratuity system for calculating the Gratuity earned by an employee based on the CTC amount:

Gratuity = 15/26* last drawn salary with allowance* a number of completed years of service.

Must Read:- Gratuity Calculator | How to Answer “What Are Your Salary Expectations?” | SDM Salary in India

Gratuity Calculation

Understanding how Gratuity is calculated is vital for both employers and employees, given its importance as a retirement benefit.

  • Gratuity calculation is categorized into sections: one for employees under the Gratuity Act and the other for those not protected.
  • The remaining drawn profits and the completed years of service are vital to compute Gratuity. The Gratuity payable is 15 days’ wages per year, derived from the common of the last 10 months’ salary.

For Organizations Covered by the Gratuity Act of 1972

If your administrative center follows the Gratuity Act, and you’ve worked for more than 5 years, your gratuity amount is calculated according to the following gratuity formula:

How is Gratuity calculated in CTC 1

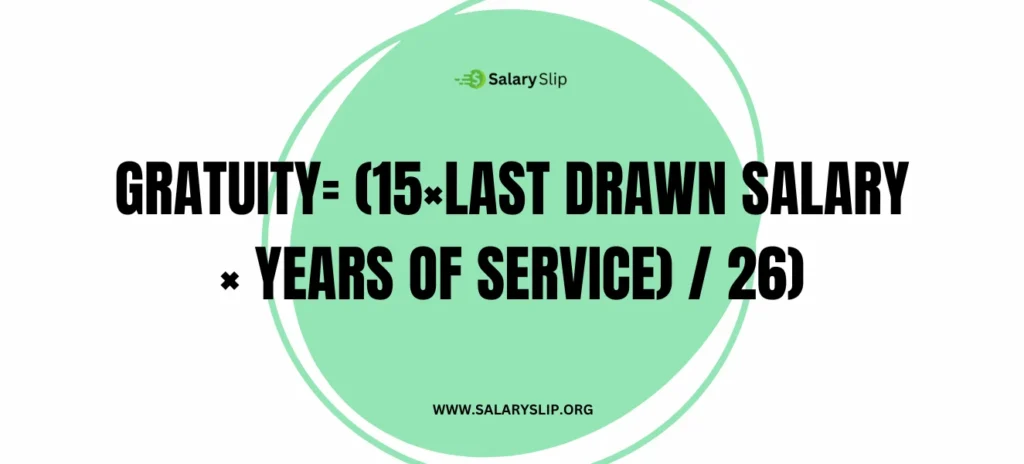
Gratuity= (15×Last Drawn Salary × Years of Service) / 26)

Let’s take an example

Mr. Sam worked at ABC Company for 11 years and 7 months, with a last-drawn salary of

INR 55,000.

Mr. Sam Gratuity Amount= (15×55,000×12)/ 26 = INR 380,769

For Organizations Not Covered under the Gratuity Act

If your place of business isn’t under the Gratuity Act, the formula for Gratuity changes a piece:

Gratuity= (15×Last Drawn Salary × Completed Years of Service) /30

For example, Mr. B labored at LMN Company for 15 years and 8 months, with a last drawn salary of INR 40,000.

Mr. B’s Gratuity Amount=(15×40,000×sixteen) / 30 = INR 3, 20,000

These examples show how Gratuity is calculated based on the rules that follow in your administrative center.

Gratuity Calculation in Case of Death of an Employee

In case of an unexpected death of an employee, the gratuity amount is going to their nominee. It is calculated based on the employee’s tenure and has a maximum limit of ₹20 lakh. The following table gives the gratuity amount payable by the Employer in case of an employee’s death.

Tax Implications Applicable to Gratuity

The taxation regulations on gratuity range for different kinds of employees. For authority employees, the gratuity amount is exempt from salary tax. However, for private employees included below the Gratuity Act, a limit is about for tax exemption on the gratuity amount.

The actual amount received by the employee and that calculated by using the above components are taken into consideration for tax exemption. The lower of the two values is relevant for tax exemption.

Consider this situation, let us think an employee acquired a gratuity of ₹9 lakh. But assume the Gratuity calculated according to components is simply ₹7 lakh. In this case, the tax exemption becomes relevant for ₹7 lakh. The stability amount, which is ₹2 lakh, can be taxable as per the existing salary tax slabs.

Conclusion

Gratuity is an important part of an employee’s salary package, and it’s far vital to apprehend how they’re calculated in the terms of CTC. The Payment of Gratuity Act of 1972 gives the strong foundation required to guarantee that employees achieve these rightful benefits as a fabric expression of appreciation for his or her continuous commitment and service.

FAQ’s:-

What is the most Gratuity payable to employees?

The most gratuity amount payable to an employee is 20 lakhs.

If the employee died during 1st to 4th year earlier than the completion of 5th year, then what would be the benefit for the employee’s nominee?

The employee’s nominee will get the gratuity payment from the Employer.

If the employee resigns at some stage in 1st to 4th year before completion of 5th year, then what will be the benefit for the employee?

The employee will not get any Gratuity Payment from the Employer.